Trust, Quality & Transparency: The Three Pillars of Ethical Leadership and Good Governance

As Public Servants we value the principles of transparency, goodness, and honesty. These are not merely individual values; they are the values of a service. They encompass ethics, morality, honesty, compassion and leadership. These are the values we try to carry throughout our careers, not only in our professional lives but also in our personal lives.
Today's topic is the role of the regulator in growth, quality and transparency. I have added to it the role of leadership that makes these principles real. I believe that, in one sense, these values may already exist and may be expected in board meetings, company affairs and governance. However, whether they are genuinely put into practice, rather than merely remaining on paper, depends on the leadership within those boards and the people managing them, from top to bottom, from the most junior employee to the most senior person in the company.
Most of you have served on the boards of private-sector organisations, although some may work in the public sector. In the private sector, boards decide how to act in accordance with their mandates and missions. We, as public servants, sit across the table from you, either framing regulations or expecting compliance with them. These regulations mean that we ask difficult questions and expect compliance. When these questions are asked and compliance is required, there may be conflict or disagreement about what is expected. You look at the matter from one perspective, while I look at it from the perspective of a regulator. That is the perspective from which we generally pursue these matters, and I use the word “pursue” very carefully.
However, I believe that boards of directors, compliance teams and regulators are all in the same boat. We are not different; we are working towards the same objective. Our approaches may differ. We expect you to be compliant and transparent, while your shareholders, clients and investors also expect you to comply with the applicable requirements.
Furthermore, companies today are not responsible only to their shareholders. They have a much wider responsibility towards their stakeholders, including the public at large. In that sense, a private company and its board of directors are also entrusted with a public responsibility. You and I must work in the same direction. We are guided by the same fundamental instinct, whether you are sitting on a board or I am sitting as a regulator. Your responsibility extends beyond shareholders, investors and creditors to your wider stakeholders. As a regulator, I am responsible to my most important stakeholder, the People. Ultimately, you, too, are responsible to them through your compliance and governance practices.
When board governance is strong, the regulator does not need to be as forceful. The regulator can be confident. However, when board governance is weak, regulation becomes the last line of defence. That last line of defence often comes into play only after the damage has been done. That is where the problem begins. Matters become difficult, and the harm may already have occurred. By that stage, the damage may be unacceptable or impossible to rectify. That is where the real issue lies.
When board governance is strong, the regulator does not need to be as forceful. The regulator can be confident. However, when board governance is weak, regulation becomes the last line of defence.
Let me share something from my own journey.
I come from a place called Tadsonna, in Beed district, a dry region. What my background taught me is that the role of institutions is crucial. Institutions stand between ordinary people and the arbitrary exercise of power. When power is exercised arbitrarily, institutions become weak and people suffer. The benefits and outcomes that people expect do not reach them.
Whenever an institution fails, the first casualties are not the strongest people in the boardroom or those at the top of the organisational ladder. They are the people who cannot defend themselves. They are the people who depend on institutions for protection and support. Without these people, neither boards nor governance would have a meaningful purpose. This, I believe, is where the role of the regulator in relation to boards becomes particularly important. Given this context, let us consider the matter from the perspective of the board and the company.
What, then, did the Companies Act, 2013, essentially ask companies to do? I will not go into the details of individual sections, as you are more familiar with them. Broadly, it asked companies to address three important areas.
1. The role of Independent Directors: This is one of the major provisions of the Act. Independent Directors existed in a rudimentary form under the earlier Companies Act of 1956, but their role was not as strongly established as it is under the 2013 Act and the framework that followed. Meeting governance expectations as an Independent Director is not merely a matter of compliance; it involves a much greater responsibility.
2. Auditors: Auditors are expected to give you figures that tell the true story, not merely numbers that the board expects to see. They are not supposed to act as rubber stamps, simply approving or providing figures that the board will accept. That is what is expected of an audit.
3. Environmental, Social & Governance issues: Although the Companies Act speaks directly about corporate social responsibility, the wider implications extend to ESG and its long-term significance.
These provisions have not emerged simply because legislators and lawmakers know what is best. They have developed through extensive deliberation and in response to repeated patterns of failure. In that sense, the present framework reflects lessons drawn from earlier failures, codified into the new Companies Act.
That is the first pillar of what I would call the regulatory framework within which directors, board leaders and management operate.
The second pillar I want to discuss is ESG regulation, which is catching up with truths that many of us already know. We do not need someone from outside to tell us these truths; we already know them. The ESG framework addresses social and governance issues, as well as the environment in which boards operate. The question is whether companies are genuinely compliant and whether they are fulfilling their social responsibilities. Much of what is presented as social compliance may look impressive in a presentation. But has it actually been implemented? Is it compliant in practice? Have the intended outcomes of the ESG framework been achieved, or do they exist only on paper?
Across India and other major economies, much early ESG reporting has been closer to marketing than to measurement. There are targets without enforcement mechanisms. There are carbon claims and offsets that have not been independently verified.
When trust breaks down, the regulatory mechanism itself is weakened. When the regulatory mechanism collapses, governance has failed and public confidence is severely damaged.
Let us consider the regulatory framework through India's Business Responsibility and Sustainability Reporting (BRSR) framework and the global standards for disclosure. These are not necessarily about inventing something new. They are intended to close a gap that already exists between what companies claim and what they actually put in place. That gap must be addressed.
The same three questions apply here.
1. Does your emissions reporting reflect actual measurement, or does it simply provide a number that your team has been asked to produce because a competitor has published one?
2. Is each target genuinely ambitious and supported by the effort required to achieve it, or has it merely been published to create an impression?
3. Would your disclosures withstand an assurance audit conducted by someone who has no relationship with your sustainability team?
These are the questions that you and I must ask ourselves. As a regulator, I must ask them of the sector as well.
What, then, does ESG offer us? At its best, ESG uses a language that boards understand, which is Disclosure & Risk. It requires us to consider stakeholders, not merely shareholders, many of whom have never had a seat at the boardroom table.
Consider the river that does not invoice your company when its factory pollutes it. Consider the community whose groundwater your company draws upon, even though the depletion of that resource may never appear as a liability on your balance sheet. These are difficult questions, but they must be asked by everyone in this room, across boards in this country and around the world.
I now come to a sector that offers a classic example of why Regulation and Regulators exist. Food and drug regulation is a classic case study.
When a company makes a mistake in a financial area, markets eventually respond. They may do so imperfectly, and the mechanisms may be rudimentary, but they can respond to what has happened. However, when a batch of medicine fails to meet the required standards, or when adulterated food is sold, the consequences can be immediate, physical and irreversible. There is no equivalent corrective mechanism for a family that has lost a child because of a contaminated or unsafe medicine. The market cannot undo that loss. This is where regulation becomes essential.
This is the role of the Food Safety and Standards Authority of India and of the Central Drugs Standard Control Organisation in pharmaceutical regulation.
An ordinary citizen buying a medicine has no independent way of verifying what it contains. The entire system rests on the premise that the product has been properly verified before it reaches the consumer. The trust that citizens place in the regulator is therefore crucial.
As we discussed before this session, how can we ensure that every plate of food, every food or drink served to us, and every product we purchase is safe? Where does the regulator come in?
Of course, a regulator cannot check everything. That is where public trust can begin to erode. When trust breaks down, the regulatory mechanism itself is weakened. When the regulatory mechanism collapses, governance has failed and public confidence is severely damaged. The question then arises:
What are public institutions doing, and what is the regulator doing?
Regulation, in this sense, is an enabling mechanism. Without it, an honest manufacturer competing on quality may struggle to survive. If regulation and the regulator are absent, products entering the market may compete on grounds that have little to do with quality or public interest.
Whether a company is trustworthy depends, over time, on the stand taken by its board and its leadership.
I would like you to consider and connect three principles: Truthfulness, Quality and Transparency. This is where compliance and the role of board members become important. It is also where the role of the regulator comes into focus. There may be three different regulatory regimes and different mechanisms, but the underlying truth is the same; regulation can mandate disclosure, but it cannot guarantee that the disclosure will be truthful. That truth must come from the individual manager and the organisation. Regulation can require a report, but it cannot guarantee that the report reflects the truth in spirit rather than merely in letter or form. That gap is precisely where leadership matters.
Regulation and leadership cannot be treated as separate cornerstones, discussed in entirely separate departments. But unfortunately, in many boards and companies, leadership operates at one level while compliance is treated as a separate department. The moment these functions are separated, the message is already clear that compliance is regarded as a question of procedure rather than a responsibility of leadership.
Boards that weather crises well are not necessarily those that have crossed off every item on a checklist or completed every form. They are the boards that take their responsibilities seriously.
I would like to leave you with three propositions.
1. Ensure that your governance and ESG claims, together with the systems used to quantify them, can withstand examination by someone who has no reason to be kind to you.
2. If they cannot, they were never expressions of truth, quality or transparency; they were merely appearances.
3. Remember that regulations exist to protect the person with the least power. They are not primarily there to protect institutional investors who can hire analysts and advisers. They are also there to protect retail shareholders, rural consumers and communities downstream that have no seat at your table.
Across company law, ESG and, for some of you, food and drug safety, I ask you to carry one thought with you; these are not three separate compliance burdens for three separate departments. They come down to one fundamental question, 'Can an institution be trusted with power, and does it choose to act honestly even when it is not compelled to do so?'
Truthfulness means not having to manufacture an additional appearance of honesty. Quality means not quietly eroding when nobody is watching. Transparency means not waiting for a regulator to demand it. These are not merely questions to be asked of an enterprise or imposed upon it. They are the principles that have always made enterprises worthy of trust.
In the end, this is what distinguishes leadership. This is where trust, transparency and leadership come together. Leadership must enable boards not merely to survive, but to thrive. I believe boards must aim to thrive rather than simply adjust to circumstances.
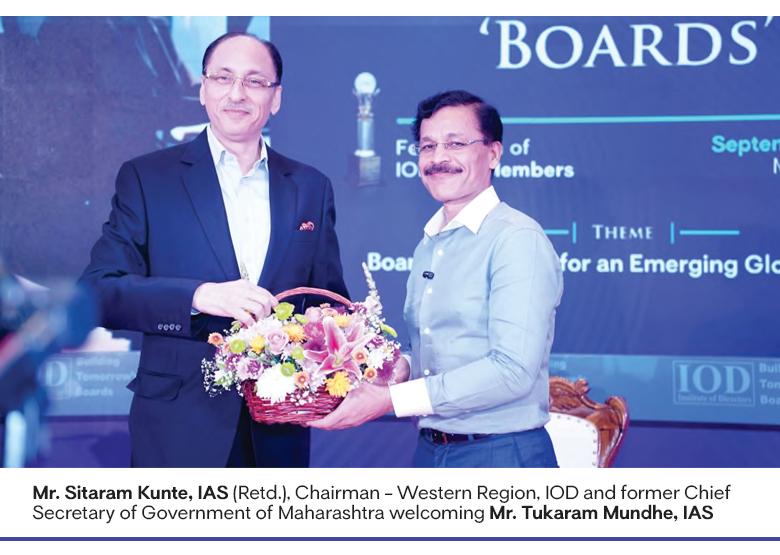
He is the Commissioner, Food and Drug Administration (FDA), Government of Maharashtra during the National Convention Series on 'Boards', held on September 05, 2026 at Taj Lands End, Mumbai, India.
Owned by: Institute of Directors, India
Disclaimer: The opinions expressed in the articles/ stories are the personal opinions of the author. IOD/ Editor is not responsible for the accuracy, completeness, suitability, or validity of any information in those articles. The information, facts or opinions expressed in the articles/ speeches do not reflect the views of IOD/ Editor and IOD/ Editor does not assume any responsibility or liability for the same.

Nov 10, 2026
In a multipolar world as middle ranking powers search for new relationships to augment their capabilities, big powers seem more willing to exert hard power and disrupt to demonstrate and exploit their ranking. The USA is led by a climate change denier who initiated a war of choice that has backfired.
Read more
Nov 10, 2026
It was well past 6.00 pm, much beyond the scheduled closing time of the Board meeting. The Directors were beginning to glance at their watches, nervous about catching their return flights to their home cities. The Chairman looked through the agenda and announced, “We have completed the key items.
Read more
Nov 10, 2026
For as long as boards have existed, they have operated at a structural disadvantage. Directors answer for a company they do not run, and most of what they learn reaches them through a single channel: the management team they are meant to oversee.
Read more
Nov 10, 2026
The days have gone when Corporate Governance in Public Sector Undertakings (PSUs) was considered merely as a regulatory obligation. The era of limited autonomy for boards for decision-making, more inclined towards social obligations rather than a commercial approach and government control has gone with the passage of time.
Read more
Nov 10, 2026
For decades, Corporate Leadership could borrow its bearings from a small circle of capitals and a shared set of assumptions. Today those bearings are scattered across a many-centred world, and boards must steer by judgement more than by precedent. It is a harder way to lead, but also a more honest one.
Read more
Oct 15, 2026
Independent Directors (IDs) should complement executive colleagues who wrestle with day-to-day issues that burn up time needed for the independent thought expected of company directors. IDs and executive directors should understand each other's roles and how their respective contributions can be complementary.
Read more
Oct 15, 2026
Boards rarely destroy value because a director did not know a section of tax law. They destroy value when obvious questions are not asked early enough, or answers are accepted because the organisation has fallen in love with a transaction. This is not confined to weak boards; it is the natural risk of enthusiastic ones.
Read more
Oct 15, 2026
The role of an Independent Director has never been more vital than in today's increasingly complex corporate landscape. Currently, businesses are navigating geopolitical uncertainty, rapid technological disruption, diverse regulatory expectations, mounting stakeholder demands, financial pressures and growing scrutiny of corporate governance.
Read more
Oct 15, 2026
Public service brings in a lot of experience across different sectors, and in some sectors one does develop deeper insights. Thus, when one joins the boardroom, one can bring in that experience, but it is equally important to keep oneself updated in the sector in which one has accepted the board position.
Read more
Oct 15, 2026
My answer has changed over the years. Earlier, I would have said that deep functional expertise especially in functions like Finance, HR and Business Operations, leadership experience and a good reputation were the foundation. I still believe they are essential
Read more
Oct 31, 2025
Aug 08, 2025

Aug 08, 2025
Aug 08, 2025

Aug 08, 2025

Aug 08, 2025
Aug 08, 2025
Jul 18, 2025

Feb 06, 2025

Nov 09, 2024
Jun 01, 2024

Mar 05, 2024